Mixed developments of raw material prices for flexible packaging in the third quarter of 2026
European prices for raw materials used in the manufacture of flexible packaging showed mixed developments in the third quarter of 2026. Following the sharp increases in the previous quarter, prices for BOPP, HDPE and LDPE declined significantly. Aluminium foil prices also fell, while paper and BOPA prices rose slightly and energy prices increased significantly. Prices for all materials monitored remained above their levels in the same quarter of the previous year.
Compared with the second quarter of 2026, prices for BOPP film (20 micron) fell by 24%. HDPE prices declined by 14% and LDPE prices by 15%. Aluminium foil (7 micron) recorded a decrease of 3%. By contrast, prices for one-sided coated paper (60 g/m²) and BOPA film (15 micron) each increased by 2%. Prices for PET film (12 micron) remained stable.
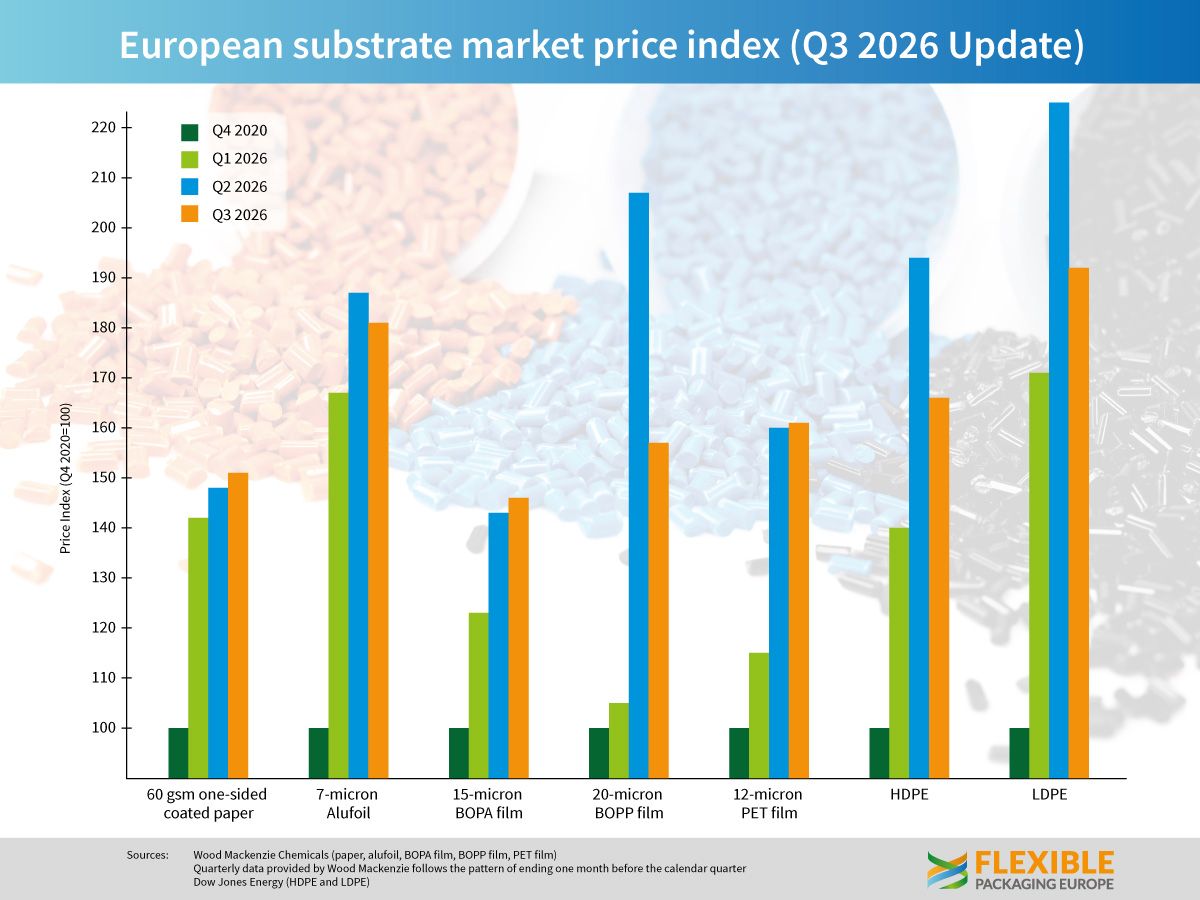
Compared with the third quarter of 2025, BOPP film prices were 41% higher. HDPE prices increased by 25% and LDPE prices by 23%. BOPA film prices rose by 18%, PET film by 16% and aluminium foil by 11%. Prices for one-sided coated paper were 2% above their year-earlier levels.
Alexander Tkachenko, Research Analyst, Films and Flexibles at Wood Mackenzie, explains the developments: “BOPET prices remained stable this quarter, despite initial hopes of a decline following the spike caused by the US–Iran conflict. PTA and MEG prices were unchanged throughout the quarter.
BOPP prices have fallen significantly from the sharp peak seen in Q2, as the supply constraints behind the initial surge have eased considerably. However, prices remain above pre-war levels. Higher PA6 and caprolactam prices this quarter have translated into a further slight increase in BOPA film prices.
Aluminium foil prices have declined, driven almost entirely by lower LME prices and warehouse premia while paper prices have edged up as energy costs remain high and pulp prices have risen slightly.”
Kaushik Mitra, Director Polyolefins at Dow Jones Energy, describes developments in the European polyethylene market: “The Q3 2026 Polyethylene market in Europe experienced significant swings in sentiment and direction. The quarter began with softer trends as raw material and energy prices slid lower, a trend already evident in late Q2-2026. Buyers became more price-sensitive, prioritized affordability and bargained harder for the resin. Buyers were aware of the risk of a sharper drop in values and what it would mean for their inventory; therefore, buying was incremental and maintaining stocks was the focus. Situation changed swiftly with renewed tension and escalation in the Middle East which spurred a strong crude oil and energy price rally. Apart from higher crude oil prices, the price of natural gas in Europe also went up as stocks are lower than usual ahead of winter. Input cost inflation added cost pressure on the polymer prices. Market participants were apprehensive of another strong price rally similar to one visible in March/ April. However, in this cycle buyers, sitting on higher inventory were less focused on material accessibility and more concerned about affordability. End buyer resistance was higher and risk of inventory impairment in the event of price correction was rising. Amid all these demands was lacklustre. July/ August are the weakest months of the year due to summer lull in activity.
September recovery was not as robust as in the past years as consumers are cautious and buying of polymers is restrained. Supply is smooth, Middle East supply is still recovering, but supply from US and Canada (both now having duty free access to European market) are rising steadily. Local production was resilient despite some outages. Overall, structurally market was balanced-to-nominally long, cost pressure is supporting price levels.”
Guido Aufdemkamp, Executive Director of Flexible Packaging Europe, comments: “Prices for all materials monitored remain above their year-earlier levels. These differing developments demonstrate how strongly individual markets are influenced by raw material costs, as well as their respective supply conditions. Despite the developments of the main substrates, the entire sector is confronted with increasing costs for energy and liquid packaging aids. The latest development of crude oil expects to raise the pressure again on many raw material costs. The geopolitical situation remains very fragile, so that disrupted exports, longer lead times and higher freight, insurance and raw material costs are permanent risks for the procurement of European converters. Reliable planning of material supply and costs therefore remains a challenge for flexible packaging manufacturers.”
